Most owners I meet know roughly what their home is worth. Far fewer know what they will actually walk away with. On a luxury sale in Los Angeles, the gap between the contract price and the wire that lands in your account can run into the hundreds of thousands of dollars, and the biggest single line item is often a tax that didn't exist before 2023.
When owners ask me about the cost to sell a luxury home in Los Angeles, I start with one question: which city is the house actually in? The answer changes the math more than almost anything else.
Here is how I walk sellers through transfer taxes, Measure ULA, closing costs, and the pricing decisions that protect the net.
Measure ULA in Plain English
Measure ULA, often called the "mansion tax," is a transfer tax the City of Los Angeles charges when real property sells above a set threshold. It applies to the full sale price, not just the amount over the line, and it sits on top of the city's regular transfer tax.
For sales closing after June 30, 2026, according to the City of Los Angeles Measure ULA FAQ:
- Up to $5,400,000: no ULA tax. The city's base transfer tax of 0.45% still applies.
- Over $5,400,000 and under $10,900,000: 4% ULA tax, for a combined city rate of 4.45%.
- $10,900,000 and above: 5.5% ULA tax, for a combined city rate of 5.95%.
The thresholds adjust every year with inflation, so I confirm the current numbers with escrow before every listing.
A Worked Example: Pricing Right at the Line
Picture a Westside home where the recent sales support a price of roughly $5.5 million. The seller's first instinct is to list at $5,550,000 and leave room to negotiate. Here is what the City of Los Angeles transfer taxes look like at two prices, using the current rates on the City of Los Angeles Measure ULA FAQ:
Sells at $5,400,000 | Sells at $5,550,000 | |
|---|---|---|
County transfer tax ($1.10 per $1,000) | $5,940 | $6,105 |
City base transfer tax (0.45%) | $24,300 | $24,975 |
Measure ULA (4%) | none | $222,000 |
Total transfer taxes | $30,240 | $253,080 |
Price minus transfer taxes | $5,369,760 | $5,296,920 |
In this example, the "higher" sale leaves the seller about $72,840 poorer. The buyer pays more and the seller keeps less. That is the kind of result pricing discipline is meant to prevent.
So in a case like this, I would set the strategy before the home goes live. If the market supports a price comfortably above roughly $5.63 million, we price for that and own it. If the realistic range sits close to the line, a price at or just under $5,400,000 can be the smarter number, and the negotiation shifts to terms instead of dollars: closing date, a rent-back period, the condition the home is delivered in. One caution: the tax is charged on the full value the buyer gives, so nothing can be moved into side payments or inflated credits to get under the line. Escrow and your tax advisor should review every term before you sign.
This is a hypothetical example for illustration, not a specific client's sale.
The Countywide Tax, the City Tax, and Why Your Address Can Mislead You
Every sale in Los Angeles County pays the Los Angeles County documentary transfer tax of $1.10 per $1,000. Only a handful of cities add their own tax on top, and the City of Los Angeles is one of them. In Los Angeles, the seller customarily pays these transfer taxes, though like most terms it can be negotiated.
Here is the part that catches people. Bel Air, Brentwood, the Hollywood Hills, Encino, and Pacific Palisades are all neighborhoods inside the City of Los Angeles, so ULA applies there. A home inside the City of Beverly Hills does not pay ULA or the Los Angeles city tax. But many homes with a 90210 or "Beverly Hills" mailing address, including much of Beverly Hills Post Office, sit inside Los Angeles city limits. The mailing address doesn't decide the tax. The parcel's city does.
To see what that means in dollars, take the same $6,000,000 sale in two places:
City of Los Angeles (e.g., Brentwood) | City of Beverly Hills | |
|---|---|---|
County transfer tax ($1.10 per $1,000) | $6,600 | $6,600 |
City base transfer tax (0.45%) | $27,000 | none |
Measure ULA (4%) | $240,000 | none |
Total transfer taxes | $273,600 | $6,600 |
That difference is larger than many owners' entire budget for staging, repairs, and marketing combined. It is also why how Beverly Hills estates are really priced and how they net out are two separate conversations.
How to Check Which City Your Home Is In
Picture an owner on a canyon street north of Sunset with a 90210 mailing address who has always described the house as "in Beverly Hills." They price it assuming no ULA, then learn in escrow that the parcel sits inside the City of Los Angeles. On a $6 million sale, that is the $273,600 difference shown in the table above, discovered at the worst possible moment.
Before I price any home near a city line, I confirm the jurisdiction from official records, not the mailing address: the parcel's city on its property tax bill and Los Angeles County Assessor record, and a parcel lookup in the City of Los Angeles zoning system (ZIMAS), which only returns results for parcels inside city limits. Then I confirm it again with escrow. It takes a few minutes and it can change the entire pricing conversation.
Hypothetical example for illustration, not a specific client's sale.
Pricing Near the Line: The $5.4 Million and $10.9 Million Cliffs
Because ULA applies to the whole price, the thresholds work like cliffs, not ramps. A home that sells for exactly $5,400,000 pays no ULA. A home that sells for $5,450,000 pays $218,000.
Run the numbers and a seller has to get to roughly $5,626,000 just to net the same amount they would have netted at $5,400,000. At the upper threshold, moving from 4% to 5.5% means a seller needs roughly $11,074,000 to match what they would have kept at just under $10,900,000.
That doesn't mean every home near the line should be priced under it. Some homes are clearly worth well above the threshold, and underpricing them to dodge a tax leaves more money on the table than the tax itself. What it does mean is that the asking price, the negotiation strategy, and which items are included in the sale all need to be planned around the line before the home goes live, not after the first offer.
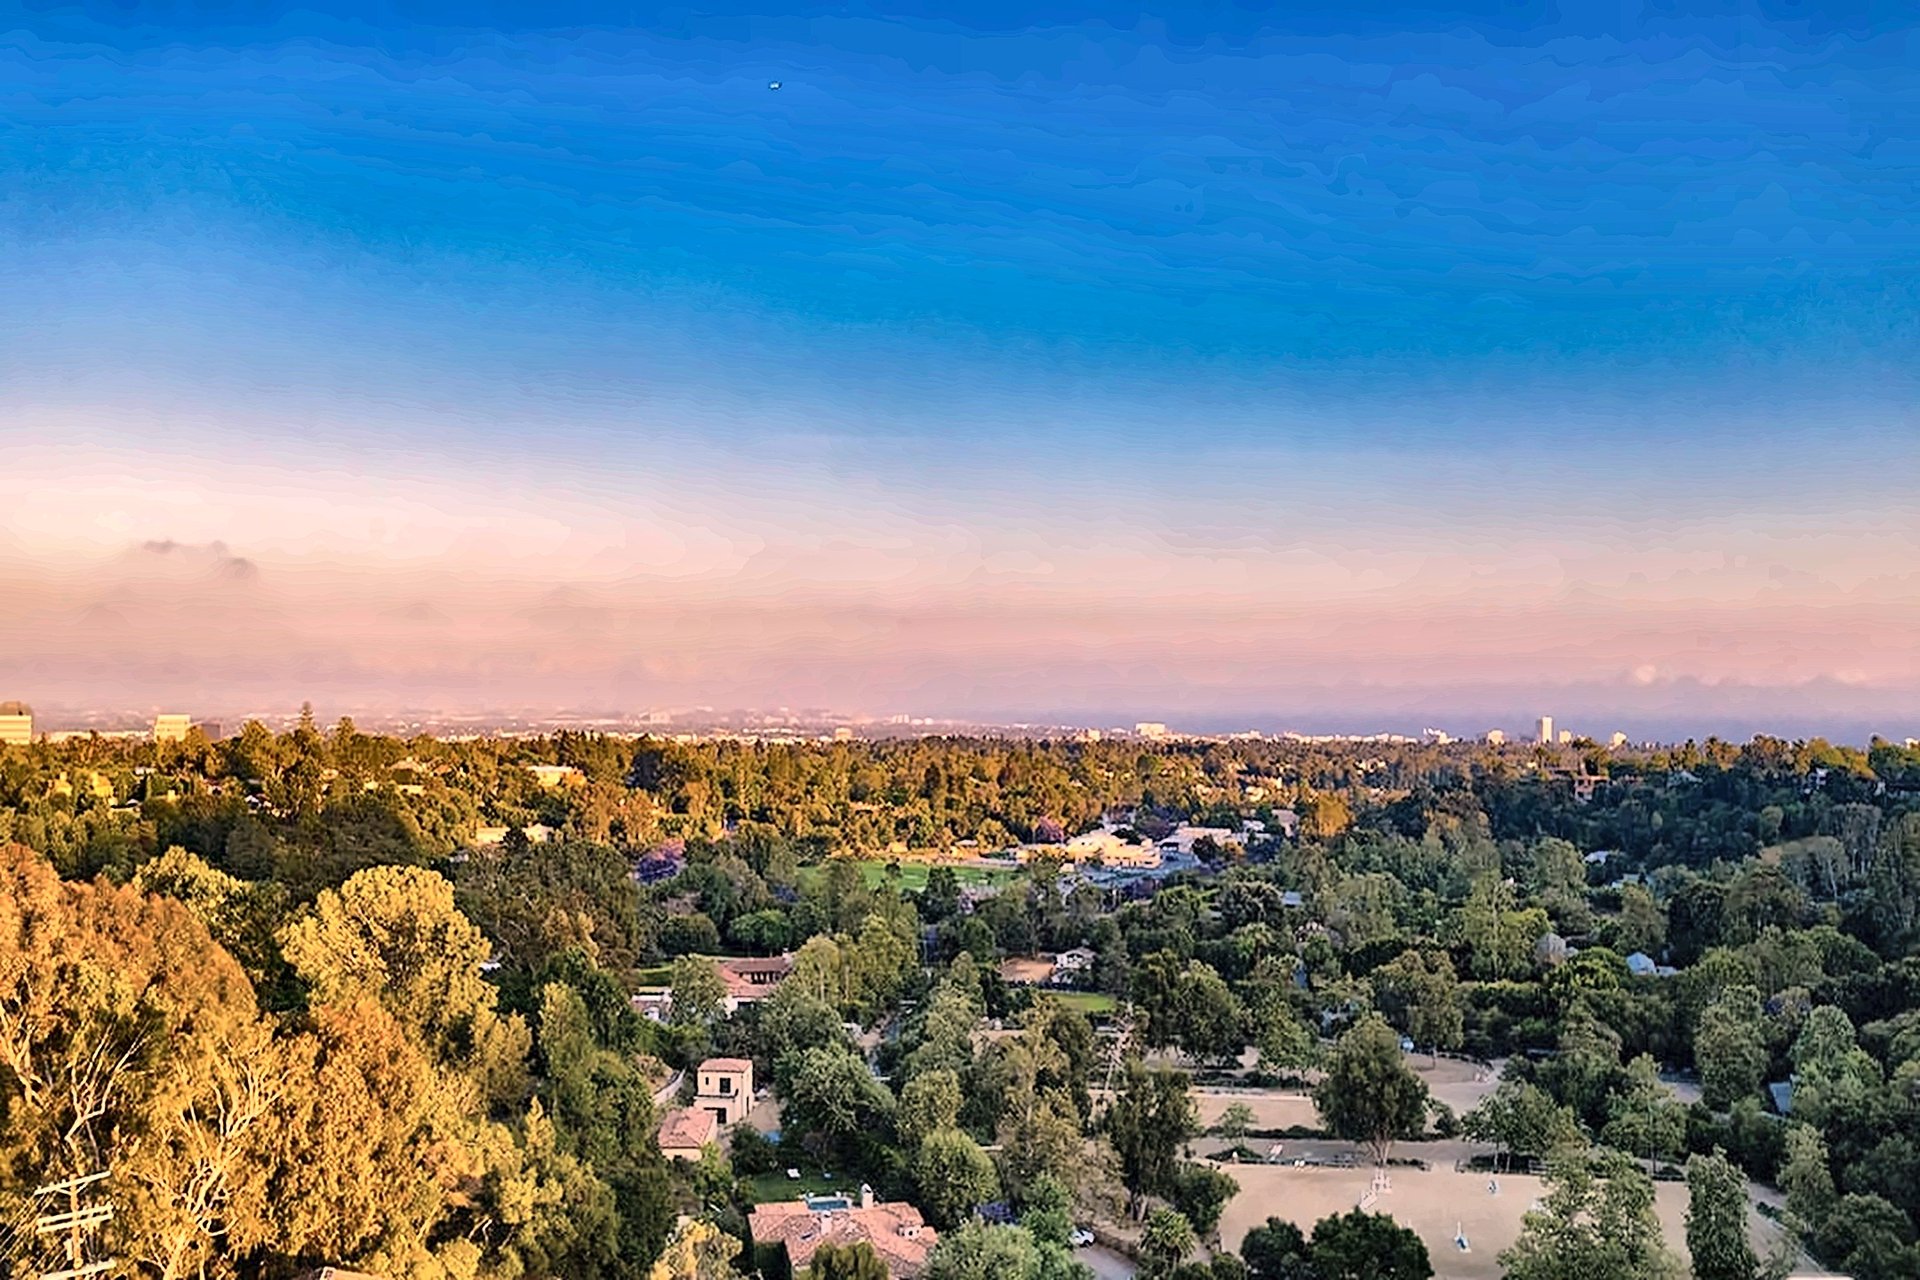
A home like a lower Mandeville Canyon estate currently offered for sale in Brentwood shows why this matters: canyon views, a private lot, and a price that sits above the first threshold. For any listing in that range, I model the seller's net at several prices before we agree on an asking price.
The Rest of the Closing Costs
Transfer taxes get the headlines, but they are not the only line items. On a luxury sale in Los Angeles, I make sure sellers budget for:
- Agent compensation. Listing and buyer agent compensation is negotiable and is set in writing. I walk through it line by line so there are no surprises.
- Escrow and title. Escrow fees and the owner's title policy, which are customarily split or allocated by local practice and the contract.
- Prorated property taxes and HOA dues. Settled through escrow up to the closing date.
- Loan payoff. Including any prepayment terms on your existing mortgage.
- Inspection repairs or credits. Most luxury buyers inspect thoroughly, and the requests that follow are a real cost even when the home is well kept.
- Preparation and carrying costs. Staging, landscaping, repairs before photos, and the mortgage, insurance, utilities, and upkeep for every month the home is on the market.
- Withholding and income tax. California requires withholding on many sales unless an exemption applies, and capital gains depend on your basis, how long you have owned the home, and whether it was your primary residence. This is a conversation for your CPA, and I bring them in early.
The Cost Sellers Most Often Forget
In my experience, the line item that surprises sellers most is not a tax. It is the cost of the weeks between "we're ready" and "we're live," plus the requests that come after the inspection.
Say a seller budgets carefully for transfer taxes and agent compensation on a $6 million sale. Then the home needs a few weeks of landscaping, touch-up paint, and repairs before photos, and the buyer's inspection turns up drainage and roof items that become a credit request at the negotiating table. None of those costs show up on a back-of-napkin estimate, but together they can easily reach the tens of thousands of dollars. The fix is simple: budget for preparation and a reasonable inspection allowance from day one, so a credit request is a planned decision and not a shock.
Hypothetical example for illustration; actual costs vary by home.
How I Build a Net Proceeds Estimate
Before we set a price, every seller I work with gets a written net proceeds estimate, not just a list price. It shows the contract price, every tax and fee, the loan payoff, and what lands in the seller's account at three or four different sale prices. When a home sits near a ULA threshold, that sheet usually changes the conversation about where to list.
Here is what a typical estimate covers, line by line:
- The sale price, shown at three or four different levels (for a home near a threshold, one of them is at or just under the line).
- County transfer tax, the city base tax, and Measure ULA, where they apply.
- Agent compensation. It is negotiable, it is agreed in writing, and I walk through exactly how it is paid so nothing about it is a surprise.
- Escrow, title, and recording costs, allocated the way the contract will allocate them.
- Prorated property taxes and any HOA dues.
- Your loan payoff, which we confirm with a payoff statement from your lender rather than an estimate.
- A preparation budget and an inspection allowance.
- The estimated amount wired to you at closing.
Escrow reviews the figures, and for anything involving capital gains, withholding, or a 1031 exchange, I bring in the seller's CPA before we set the price, not after we accept an offer.
If carrying costs are high or the market for your price point is thin, it is also worth thinking through whether to rent out or sell first. And once you're in contract, knowing what happens after you accept an offer helps you plan the timing of the closing and the move.
When Carrying Costs Cost More Than a Price Adjustment
Carrying costs are the quiet part of the math. Say an owner is carrying an $8 million home at about $40,000 a month once you add the mortgage, property taxes, insurance, utilities, gardeners, pool service, and staff. If the home sits six extra months waiting for a buyer at the original price, that is roughly $240,000 gone, the same as a 3% price reduction, and the home is still unsold. A stale listing also invites lower offers, so the price often comes down anyway.
My advice to an owner in that position is the same advice I give on pricing generally: price it right from the start, and if the market tells you otherwise, adjust early. At the luxury level today, Measure ULA has made many buyers more cautious, and the homes that sell are the ones priced to the market rather than to the owner's hopes. Getting the deal done at the right price beats chasing the wrong one for another season.
Hypothetical example for illustration; your carrying costs will differ.
A Note for Palisades Owners
A City of Los Angeles measure on the November 2026 ballot would exempt qualifying residential properties damaged or destroyed in the Palisades Fire from the ULA tax when they are sold by the owner of record between January 7, 2025 and January 6, 2030. If you own a fire-affected property, wait for the result and confirm eligibility with escrow before you set a price.
Frequently Asked Questions
Does Measure ULA apply in Beverly Hills? Not inside the City of Beverly Hills. It does apply to homes inside the City of Los Angeles, including many homes with a Beverly Hills mailing address in Beverly Hills Post Office. Check the parcel's city before you price.
Who pays the transfer tax when selling a home in Los Angeles? By local custom the seller usually pays the county and city transfer taxes, including ULA, but it is a negotiable term of the contract.
Is Measure ULA charged only on the amount over $5.4 million? No. It applies to the full sale price once the price is over the threshold.
What does it cost to sell a luxury home in Los Angeles in total? It depends on the city, the price, your loan, and the terms you negotiate. The only reliable answer is a written net proceeds estimate built for your home.
Plan the Net Before You Pick the Price
The list price is what the market sees. The net is what you keep. The owners who do best are the ones who see both numbers side by side before the first photo is taken.
If you're thinking about selling in Bel Air, Brentwood, the Hollywood Hills, Beverly Hills, or anywhere in greater Los Angeles, request a net proceeds estimate and I will build one for your home. You can also call or WhatsApp me at 323.238.5225.
Tax figures are general information based on published City of Los Angeles and Los Angeles County rates for closings after June 30, 2026. Confirm current rates and your own tax situation with your escrow officer and CPA.
About the author: Jordan Pollack is the broker and founder of LA Luxuries Estate Agency in Beverly Hills. He sells and rents fine homes across Los Angeles and personally manages every client relationship. Meet Jordan.
G-d Bless,
Jordan Pollack, LA Luxuries, DRE 02010832